Rates Are Up. REITs Are Up.
Maybe We’ve Been Asking the Wrong Question.
Many of our clients have asked the same question this year: If long-term interest rates have been rising, why have U.S. REITs been rising too?
The question makes intuitive sense. Real estate is capital intensive. Higher interest rates can increase financing costs, pressure property values and make bond yields more competitive with REIT dividends. For years, investors have therefore relied on a familiar shorthand: rates up, REITs down. The problem is that history does not support that conclusion nearly as well as many investors assume.
REITs Don’t Move on Rates Alone
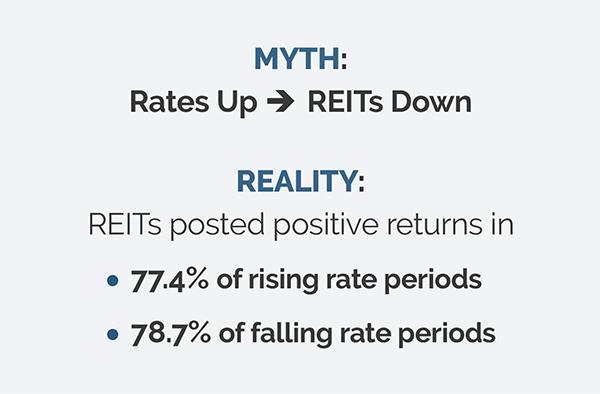
From 1992 through the first quarter of 2026, REITs generated positive rolling four quarter returns in 77.4% of periods when the 10-year Treasury yield was rising. When the 10-year yield was falling, REITs produced positive returns 78.7% of the time.1 That is a remarkably small difference.
FTSE Nareit All Equity REITs | Q1 1992 to Q1 2026
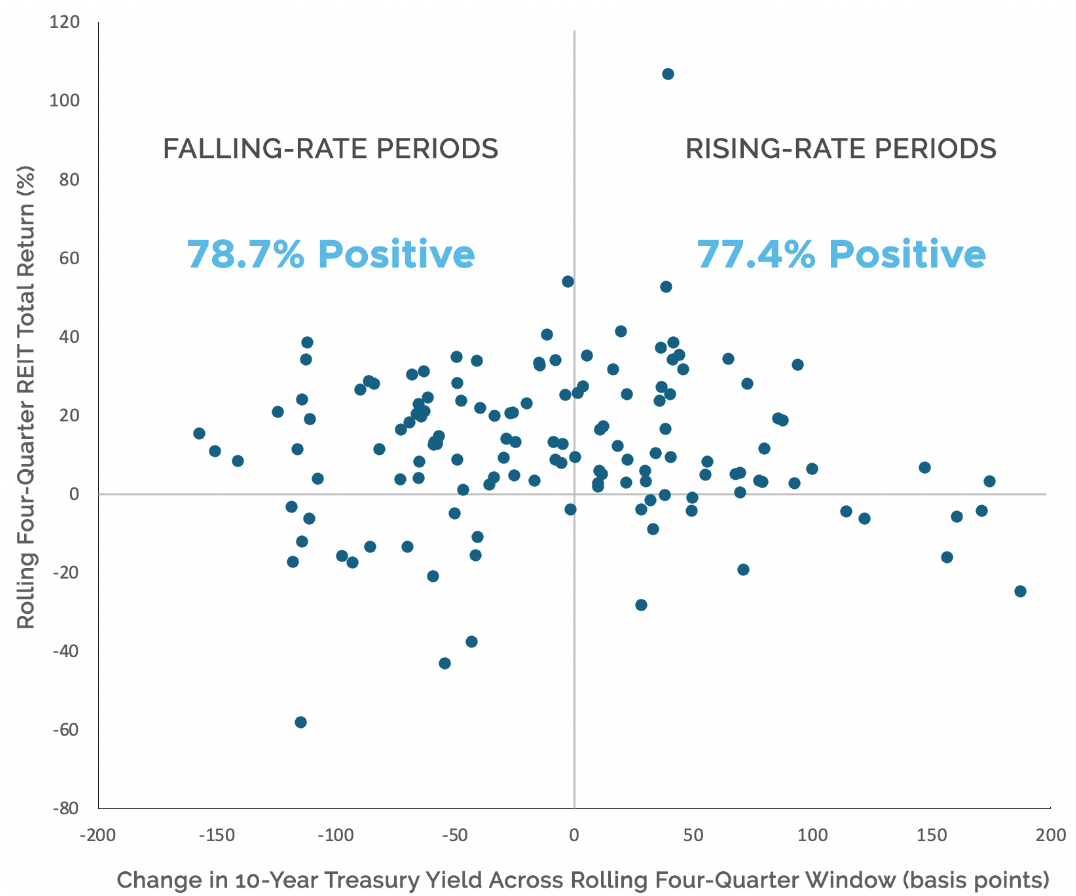
Source: Nareit, Federal Reserve/FRED. Based on 137 rolling four-quarter periods. Observation window: Q1 1992 through Q1 2026.
In other words, knowing whether Treasury yields were rising or falling historically told investors surprisingly little about whether REITs would make money.
That does not mean interest rates are irrelevant. They clearly matter – shaping discount rates, capitalization rates, refinancing costs and the economics of external growth. But rates are only one part of the equation. Just as important is why rates are moving.
Rising yields associated with stronger economic activity can coexist with improving occupancy, stronger rent growth and better property level cash flows. Conversely, falling rates are not necessarily good news if they are falling because markets expect recession and weakening earnings. The direction of rates matters. The economic environment surrounding those rates matters more.
2026 Is a Useful Case Study
This year illustrates the point particularly well. Through September 1, U.S. REITs have generated strong positive returns even though the 10-year Treasury yield has moved materially higher. The market has not stopped caring about interest rates. Rather, earnings growth, constrained supply and attractive starting valuations have been strong enough to outweigh the rate headwind.
The range has been striking: lodging and data centers are up more than 30%, health care is up 25%, while telecommunications and gaming are negative.
Year-to-Date Total Returns Through September 1, 2026
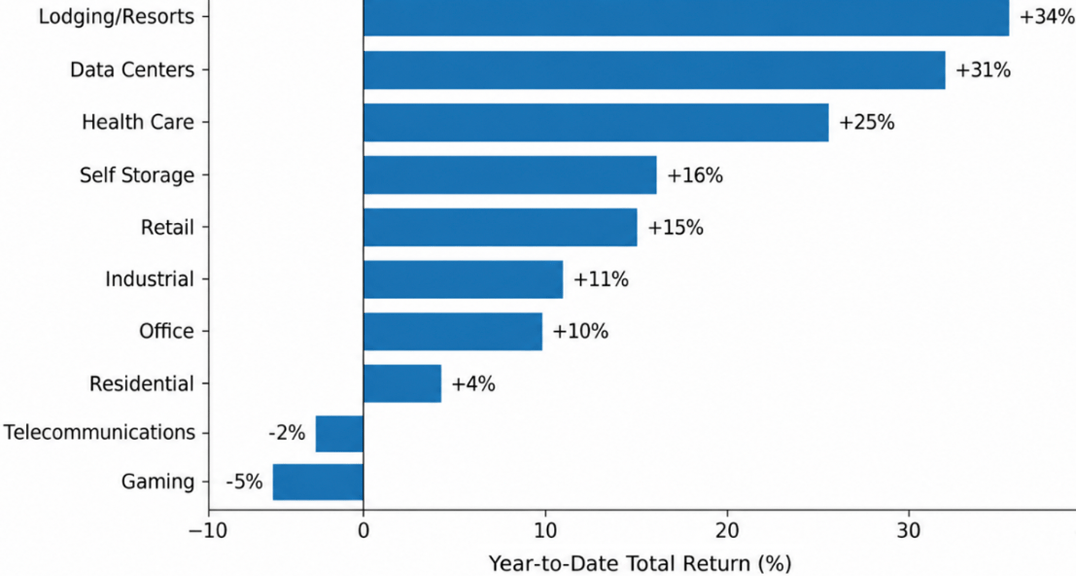
Source: Nareit. FTSE Nareit U.S. Real Estate Index Series. Data as of 09/01/2026.
A Better Question for Investors
We think investors may be better served by asking a different question. Instead of simply asking, “Where is the 10-year Treasury going?” a more useful question is: Which real estate companies can grow cash flow faster than the market expects, and what price are investors paying for that growth?
That distinction becomes especially important when performance differences between property types and individual companies begin to widen. Interest rate exposure remains part of our analysis. But it is not the analysis.
Interest-rate exposure remains part of our analysis. But it is not the analysis.”
Property-level cash flow growth, supply and demand, valuation, balance sheet structure and capital allocation all contribute to long-term returns. Increasingly, we believe the opportunity lies in identifying situations where the market is mispricing those fundamentals. Investors waiting for lower Treasury yields before buying REITs may be waiting for the wrong signal.
History suggests that the direction of rates alone tells us surprisingly little about whether REITs will generate positive returns. What matters more is whether property cash flows are improving, whether companies can convert that growth into shareholder value, and whether those prospects are already reflected in their stock prices. In 2026, the market is rewarding those differences.
1 As measured by the FTSE Nareit All Equity REITs, Federal Reserve / FRED, 10-Year Treasury, Q1 1992 through Q1 2026.
IMPORTANT INFORMATION
© 2026. Easterly Asset Management. All rights reserved.
As of June 30, 2026, Easterly Asset Management and its Strategic Partners had nearly $3.7B in managed assets which includes $3.5B in assets under management and administration of Easterly Investment Partners LLC, an SEC registered investment adviser. Easterly Snow and Easterly Ranger are investment teams of Easterly Investment Partners LLC. EAB Investment Group LLC (d/b/a Easterly EAB) and Orange Investment Advisors LLC (d/b/a Easterly Orange) are separate SEC-registered investment advisers that are strategic partners of Easterly. Each investment adviser’s Form ADV is available at www.sec.gov. Registration does not imply and should not be interpreted to imply any particular level of skill or expertise.
No funds or investment services described herein are offered or will be sold in any jurisdiction in which such an offer or sale would be unlawful under the laws of such jurisdiction. No such fund or service is offered or will be sold in any jurisdiction in which registration, licensing, qualification, filing or notification would be required unless such registration, license, qualification, filing, or notification has been effected.
The material contains information regarding the investment approach described herein and is not a complete description of the investment objectives, risks, policies, guidelines or portfolio management and research that supports this investment approach. Any decision to engage the Firm should be based upon a review of the terms of the prospectus, offering documents or investment management agreement, as applicable, and the specific investment objectives, policies and guidelines that apply under the terms of such agreement. There is no guarantee investment objectives will be met. The investment process may change over time. The characteristics set forth are intended as a general illustration of some of the criteria the strategy team considers in selecting securities for client portfolios. Client portfolios are managed according to mutually agreed upon investment guidelines. No investment strategy or risk management techniques can guarantee returns or eliminate risk in any market environment. All information in this communication has been obtained from sources believed to be reliable but cannot be guaranteed. Investment products are not FDIC insured and may lose value.
Investments are subject to market risk, including the loss of principal. Nothing in this material constitutes investment, legal, accounting or tax advice, or a representation that any investment or strategy is suitable or appropriate. The information contained herein does not consider any investor’s investment objectives, particular needs, or financial situation and the investment strategies described may not be suitable for all investors. Individual investment decisions should be discussed with a personal financial advisor.
Any opinions, projections and estimates constitute the judgment of the portfolio managers as of the date of this material, may not align with the Firm’s opinion or trading strategies, and may differ from other research analysts’ opinions and investment outlook. The information herein is subject to change without notice and may be superseded by subsequent market events or for other reasons. Easterly assumes no obligation to update the information herein.
References to securities, transactions or holdings should not be considered a recommendation to purchase or sell a particular security and there is no assurance that, as of the date of publication, the securities remain in the portfolio. Additionally, it is noted that the securities or transactions referenced do not represent all of the securities purchased, sold or recommended during the period referenced and there is no guarantee as to the future profitability of the securities identified and discussed herein. As a reminder, investment return and principal value will fluctuate.
The indices cited are, generally, widely accepted benchmarks for investment performance within their relevant regions, sectors or asset classes, and represent non managed investment portfolio. It is not possible to invest directly in an index.
This communication may contain forward-looking statements, which reflect the views of Easterly and/or its affiliates. These forward-looking statements can be identified by reference to words such as “believe”, “expect”, “potential”, “continue”, “may”, “will”, “should”, “seek”, “approximately”, “predict”, “intend”, “plan”, “estimate”, “anticipate” or other comparable words. These forward-looking statements or other predications or assumptions are subject to various risks, uncertainties, and assumptions. Accordingly, there are or will be important factors that could cause actual outcomes or results to differ materially from those indicated in these statements. Should any assumptions underlying the forward-looking statements contained herein prove to be incorrect, the actual outcome or results may differ materially from outcomes or results projected in these statements. Easterly does not undertake any obligation to update or review any forward-looking statement, whether as a result of new information, future developments or otherwise, except as required by applicable law or regulation.
Past performance is not indicative of future results.
20260914_5919386
1 As measured by the FTSE Nareit All Equity REITs, Federal Reserve / FRED, 10-Year Treasury, Q1 1992 through Q1 2026.
RISKS & DISCLOSURES
Investors should carefully consider the investment objectives, risks, charges and expenses of the Fund. This and other important information about the Fund is contained in the prospectus which should be read carefully before investing. To obtain a prospectus or summary prospectus which contains this and other information, visit funds.easterlyam.com or call Easterly Securities LLC at 888-814-8180. Performance data quoted represents past performance. Past performance is not indicative of future results. The investment return and principal value of an investment will fluctuate so that an investor’s shares, when redeemed, may be worth more or less than their original cost. Current performance may be lower or higher than the performance data quoted. All results are historical and assume the reinvestment of dividends and capital gains. Performance shown reflects contractual fee waivers. Without such waivers, total returns would be reduced. Please click here to view standardized performance for the Fund.
The Easterly funds are distributed by Easterly Securities LLC, member FINRA/SIPC. Easterly Investment Partners LLC is an affiliate of Easterly Securities LLC. Orange Investment Advisers, LLC and EAB Investment Group, LLC are not affiliated with Easterly Securities LLC.
Easterly Investment Partners LLC is an SEC registered investment adviser. Easterly Snow and Easterly Ranger are investment teams of Easterly Investment Partners LLC. EAB Investment Group LLC (d/b/a Easterly EAB) and Orange Investment Advisors LLC (d/b/a Easterly Orange) are separate SEC-registered investment advisers that are strategic partners of Easterly. Each investment adviser’s Form ADV is available at www.sec.gov. Registration does not imply and should not be interpreted to imply any particular level of skill or expertise.
Not FDIC Insured-No Bank Guarantee-May Lose Value.
IMPORTANT FUND RISK
Risks of real estate fund ownership are similar to those associated with direct ownership of real estate, such as changes in real estate values, interest rates, cash flow of underlying real estate assets, supply and demand and the creditworthiness of the issuer. International investing poses special risks, including currency fluctuations and economic and political risks not found in investments that are solely domestic. Options involve risk and are not suitable for all investors. Writing a covered call option allows the Fund to receive a premium (income) for giving the right to a third party to purchase shares that the Fund owns in a given company at a set price for a certain period of time. There is no guarantee of success for any options strategy. Increased Fund turnover may result in higher brokerage commissions, dealer mark-ups and other transaction costs and may result in taxable capital gains. Investments in lesser-known, small and medium capitalization companies may be more vulnerable to these and other risks than larger, more established organizations.
Diversification does not guarantee a profit nor protect against loss in any market.
202600914_5919379